Link REIT full year (FY2024) results beat expectations.
Today, Link Reit (0823.HK) reported full year results that beat analysts' expectations. Revenue increased year-on-year by 11% to 13.578 billion HK$, while net property income grew 9.5% to 10.07 billion HK$. The full year distributable income came in at 6.718 billion HK$, a 6.4% increase from FY2023. The company declared a final dividend payout for FY2024 of 1.3257 HK$ per unit (11.6% gain year-on-year), bringing the full year distribution per unit to 2.6265 HK$. Even though the FY 2024 DPU experienced a 4.3% drop compared to FY 2023, it still handily beat the analysts average estimate of 2.567 HK$ as discussed in this earlier post. Consequently, the stock rose today to close at 34.70 HK$.
The net gearing ratio remains at a healthy level of 19.5% and the NAV per unit experienced a decrease of 5.4% to 70.02 HK$. Nevertheless, Link REIT is currently trading at more than 50% discount to NAV.
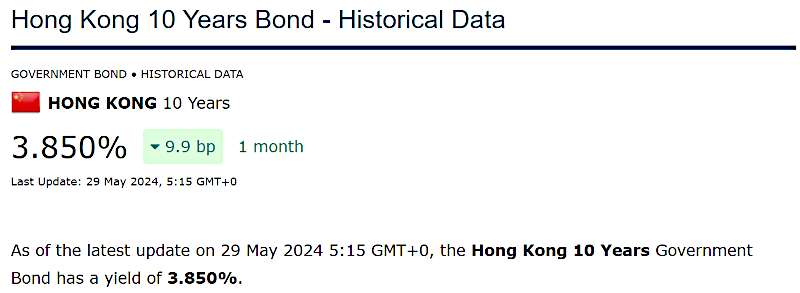
At a dividend yield of 7.57%, Link REIT still offers a relatively attractive spread over 3.72% over the current Hong Kong 10 Year Government Bond yield of 3.85%.
Some key highlights from the results presentation:
- Hong Kong portfolio tenant sales has recovered to exceed pre-Covid levels.
- Mainland portfolio enjoyed positive rental reversion of 2.8%.
- Australia and Singapore retail performance have begun contributing to the overall portfolio.
- Asset enhancement initiatives (AEI) in Hong Kong and Mainland China achieved double-digit return on investment (ROI).
- In Hong Kong, the 4 completed AEIs achieved ROI ranging from 10% to 16%, while the AEI in mainland registered ROI of 12%..
- Average borrowing cost kept at 3.78%. Investment grade credit ratings by all three major credit rating agencies.
- Half-yearly distribution per unit reversed a multi-year downtrend by registering a growth of 1.9%.
- Hong Kong retail portfolio occupancy remains high, at 98.0% while enjoying positive rental reversion of 7.9%. Tenant sales growth remains positive at 0.4% year-over-year.
- Hong Kong carparks experienced revenue growth of 3.4% and valuation gains of 2.6%.
- Singapore portfolio experienced positive rental reversion of 9.6%.
- The occupancy rate of the Australian Portfolio increased to 99.7%.
- Mainland China portfolio occupancy rate isn96.6% and enjoyed a positive rental reversion of 2.8%.
- The logistics portfolio on mainland China has an occupancy rate of 96.2% and enjoyed annual rental escalation of 3% to 5%.
- EBITDA interest coverage is at a healthy 4.3X.
- Total value of Investment Property increased by 3% halfyear-over-halfyear